
kelliray632737
About kelliray632737
Seven Superb Equity Hacks
 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
In markets where builders have added meaningful supply in recent years, prices have pulled back. Markets that overheated fastest have cooled most noticeably. But those are the exceptions. Most markets are not working from excess; they are working from scarcity.
 Affordability, by the standard measure of what share of median household income goes toward the monthly payment on a median-priced home, is near its worst level since the early 1980s. That is a real problem, and it is not going away quickly. But affordability being stretched does not mean prices are about to fall sharply. What it means, practically, is that the buyer who can close confidently has more leverage than the headline numbers suggest.
 Before you look at a single listing, get your pre-approval locked down. Not a rough estimate. Not a verbal confirmation from a loan officer you met once. A full pre-approval based on verified income, tax returns, bank statements, and a hard credit pull. Without that letter, you are not a buyer, you are a browser.
The inspection is where the marketing copy meets reality. Show up for it even if it costs you half a day of work. A good home inspector will walk you through what they are finding as they go, and you will learn more about the property in three hours than in any number of showing visits.
 Negotiation works best when it is quiet and well-prepared. Before you make an offer, find out whether there are other offers on the table or offers that have already fallen through. A listing that has been relisted after a cancellation is a fundamentally different negotiation than a fresh listing in a neighborhood where homes sell in under a week.
 For buyers with the financial cushion to handle a repair bill without panic, this market is full of opportunity that distracted or impatient buyers miss. The homes that are priced correctly for current conditions are still moving. They are going to the buyers who treated the process like the major financial decision it is.
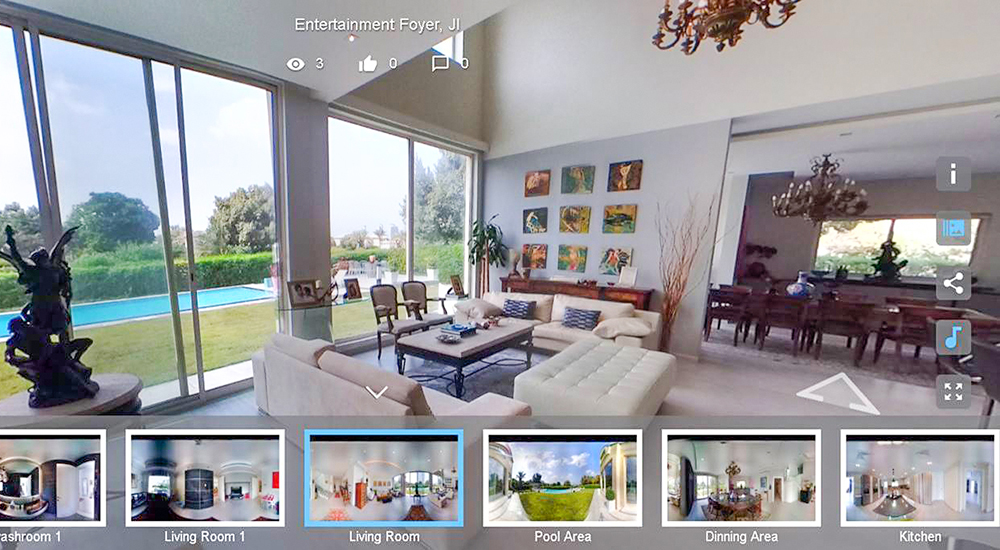 The buyers who come out ahead in this market are not the ones who waited for perfect conditions. They are the ones who got their finances in order early. Getting across current property listings in your target area is the logical first move once your financing is sorted.
No listing found.